Is your investment property still working for your retirement?


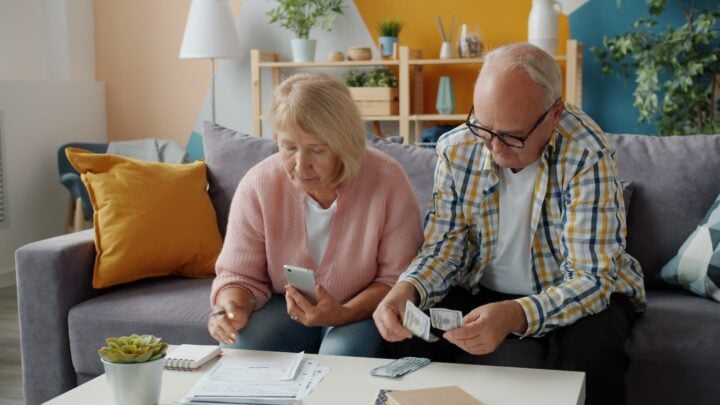
An investment property can look reassuring on paper, especially after years of rising prices, but when retirement arrives the amount left after the bills are paid becomes a much more personal measure of success.
New national research suggests property investors are reconsidering those sums as borrowing costs and changes to housing taxes reshape buying decisions.
The PropTrack–Terri Scheer Investor Report 2026 found the number of new investor loans fell 9 per cent in the June quarter, compared with a 3 per cent decline in owner-occupier loans.
However, investor loans for buying or building new homes rose 24 per cent. The report also identified a shift in interest towards properties offering higher rental yields.
For someone approaching retirement, that raises a practical question: how much income does a rental property actually leave available to spend?
Consider a hypothetical property worth $700,000, renting for $600 a week. Its annual rent of $31,200 represents a gross yield of about 4.5 per cent, assuming it is occupied all year.
That figure comes before mortgage interest, rates, insurance, maintenance, management fees and any strata charges. A vacant month or unexpected repair can further reduce the money available for everyday living.
The tax distinction owners need to understand
The federal government’s negative gearing changes take effect from July 1, 2027, but preserve existing arrangements for properties held before the May 12, 2026 budget announcement.
For established properties acquired after that announcement, losses will generally be deductible against residential property income, with unused losses carried forward, rather than offset against wages. New builds retain different treatment. Separate capital gains tax changes concern gains arising after July 1, 2027.
Those distinctions make purchase dates and individual circumstances important before making decisions about a sale or another purchase.
Start with what reaches your bank account
A useful retirement review brings together the property’s annual income, actual expenses, remaining debt and a realistic allowance for repairs and vacancies.
It should also consider how comfortably those expenses could be covered once employment income stops.
A higher advertised yield alone cannot answer those questions. The useful number is what remains after costs, and whether that amount supports the retirement you have planned.
General information only. Seek qualified tax and financial advice before acting.


 Proudly Australian owned and operated
Comments 0
Join the conversation. Comments are reviewed before they appear.
Be the first to comment.
Join the conversation
Tell us who you are to post a comment. We'll remember you next time.