Is your extras cover actually worth the money?


Dental, glasses, physio, hearing. Extras can sound impressive on paper, but there is one simple calculation that tells you how much value you are really getting.
Here is a 20-minute health insurance exercise that could be worth doing before your next premium lands.
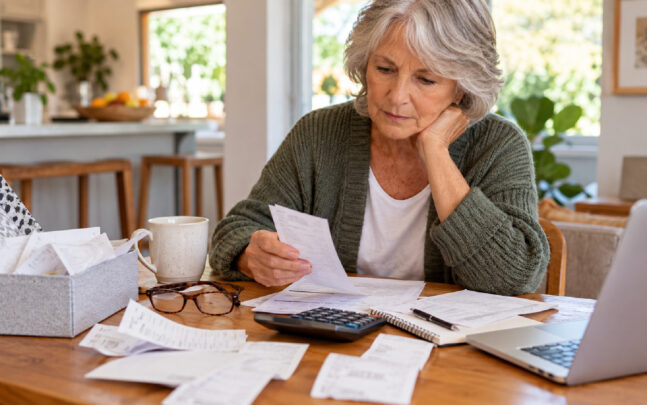
Find out how much you paid for extras cover over the past 12 months. Then find out how much your health fund paid back.
Two numbers.
The result does not automatically tell you to keep or cancel your extras, but it gives you something far more useful than a list of benefits you might use: what your policy actually did for you.
And, unlike hospital cover, extras can be reviewed separately. You can hold hospital cover without extras, extras without hospital cover, or buy the two separately.
COMPARE YOUR HEALTH INSURANCE WITH STARTS AT 60 HERE
The numbers are worth a look
CHOICE recently highlighted the gap using industry data.
It puts the average annual extras benefit paid by health funds at around $475 per person. By comparison, CHOICE calculated the average extras premium for a single person in NSW at around $936 a year before the government rebate.
That does not mean the average person is automatically losing $461.
The figures are not a like-for-like measure of every individual’s policy, circumstances or rebate entitlement, and premiums vary between states, products and households.
But they make a useful point.
Extras cover generally pays towards services such as dental treatment, physiotherapy, glasses and contact lenses. Policies commonly limit either the percentage of the bill they will pay or the amount you can claim during a year.
That means the important figure is not the impressive-looking list of services on the brochure.
It is what you paid versus what you got back.
CHECK YOUR OWN NUMBERS
Extras premiums paid in the past 12 months: $______
Benefits paid back by your insurer: $______
Difference: $______
Then ask one more question: would you have paid for those treatments anyway if you did not have extras cover?
Your needs change. Has your policy?
A policy that suited your household 10 or 15 years ago may be a poor guide to what you need today.
Maybe children have come off the policy, or perhaps the services you use most now are dental, optical, physiotherapy or podiatry.
Or maybe you barely claim at all.
Pull out your policy information and look at every category you are paying to have covered and put a tick beside everything you have claimed in the past two years.
The result can be revealing.
This is also where annual limits and sub-limits become important.
An extras policy might include dental, for example, but that does not mean every dental bill will be paid in full. Government guidance notes that policies can pay a set percentage of a treatment cost or impose an annual dollar limit.
Major treatments can have their own limits and conditions.
The word “covered” therefore does not necessarily mean “paid for”.
Hearing? Check the government program first
Hearing is particularly worth investigating before assuming private extras is your only option.
The Australian Government Hearing Services Program provides subsidised hearing services and devices to eligible Australians.
Eligibility for its voucher scheme includes people aged 21 and over who meet residency requirements and hold a Pensioner Concession Card, as well as eligible Department of Veterans’ Affairs card holders and some other groups.
One important distinction: holding a Commonwealth Seniors Health Card alone does not make you eligible for the voucher scheme.
Eligible clients can access subsidised hearing assessments and services, and a range of fully subsidised hearing devices is available. People may also choose devices with additional features and pay the difference.
So before calculating the value of hearing benefits within an extras policy, check whether you qualify for the government program and what it provides.
Dental deserves similar investigation.
Public dental services are provided by state and territory governments, with eligibility rules varying depending on where you live. For someone who qualifies, public dental may provide another option alongside private treatment and extras insurance.
Four things to check before renewing
Start with your annual limits. How much could you have claimed last year, and how much did you actually use? A large theoretical limit has little value if you never get close to it.
Next, check the benefit for the treatments you really use. Do not stop at “dental included” or “optical included”. Find out what the fund actually pays towards your regular dentist, glasses, physio or other services.
Then look for sub-limits and service limits. A policy can have an overall benefit limit while placing tighter restrictions on particular treatments. Read the policy details rather than relying on the headline number.
Finally, ask whether your hospital and extras need to remain together. They are separate forms of cover. The Australian Government confirms consumers can buy combined cover or mix and match separate hospital and extras policies.
That opens up more possibilities than simply keeping everything or cancelling everything.
Extras and hospital cover are different decisions
This distinction becomes particularly important if you are considering cutting costs.
Dropping hospital cover can have consequences under Lifetime Health Cover if you remain without appropriate hospital cover beyond the permitted absence rules. Returning to or upgrading hospital cover can also involve waiting periods.
Lifetime Health Cover does not apply to extras. But that does not mean you can drop extras today and necessarily reclaim everything immediately if you rejoin later.
Waiting periods for extras are determined by individual insurers. Government guidance says they generally range from two to six months for services such as general dental, optical and physiotherapy, while major items such as orthodontics or hearing aids can carry waiting periods of 12 months or more.
Changing to a policy with higher benefits can also trigger waiting periods for those increased benefits.
So check before you jump.
The Cover Check
The Government’s planned private health insurance rebate changes from April 2027 also matter here because the rebate can apply to eligible hospital cover, extras cover, or both.
That makes now a sensible time to understand what you have rather than waiting for another premium notice.
Pull up your claims history. Find your premium. Put the two numbers beside each other.
If extras has paid back strongly on dental, optical, physio or other services you would have purchased anyway, you may decide it is doing exactly what you want.
If the gap makes you wince, at least you now know what question to ask.
Worth knowing where you stand?
You can compare your health insurance with Starts at 60, or talk it through with an Australian adviser on 1800 31 23 60. There is no obligation and no pressure to switch – plenty of people call simply to find out whether their current cover still stacks up.
We’ll be following the legislation through to the Senate committee report in October and will come back to what it means from there. If you have a question about your own situation, leave it in the comments below. We read them, and they help shape what we cover next.
ALSO CHECK OUT IS PRIVATE HEALTH INSURANCE WORTH IT IN RETIREMENT?
IMPORTANT LEGAL INFO This article is of a general nature and FYI only, because it doesn’t take into account your personal health requirements or existing medical conditions. That means it’s not personalised health advice and shouldn’t be relied upon as if it is. Before making a health-related decision, you should work out if the info is appropriate for your situation and get professional medical advice.


 Proudly Australian owned and operated
Comments 0
Join the conversation. Comments are reviewed before they appear.
Be the first to comment.
Join the conversation
Tell us who you are to post a comment. We'll remember you next time.