Is private health insurance worth it in retirement?


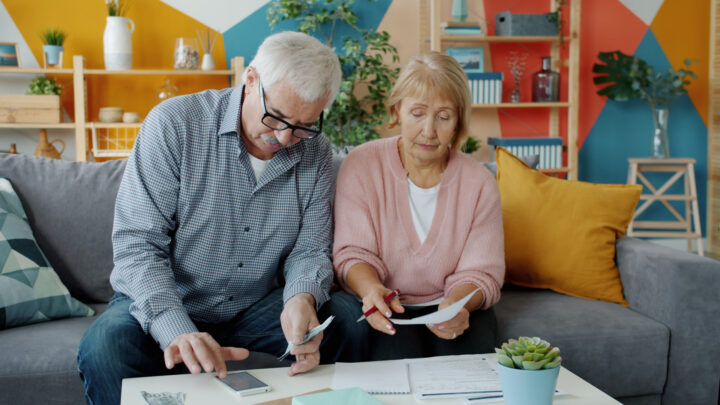
It is the question sitting behind every premium notice. Once the pay packet stops, does private health insurance still earn its place in the household budget?
Ask a room of over-60s whether private health insurance is worth the money and you will get a fiercely divided response — and both sides will have a story to back it up.
One person has held cover for 40 years, barely claimed and calculates they have paid tens of thousands of dollars for very little return. Another needed a hip replacement, chose their specialist and had surgery without a long wait. They would not dream of giving it up.
Both experiences are real, but neither answers the question for you.
That is what makes the decision difficult in retirement. The calculation changes when wages stop, household income falls and health care starts taking up a bigger part of the picture.
So forget the sales pitch for a moment. Let’s look at the maths.
COMPARE YOUR HEALTH INSURANCE WITH STARTS AT 60 HERE
First, clear away the tax arguments
Three financial considerations tend to come up whenever private health insurance is discussed: the Medicare Levy Surcharge, Lifetime Health Cover loading and the Australian Government Private Health Insurance Rebate.
They are not the same thing.
The Medicare Levy Surcharge is an additional tax of between 1 and 1.5 per cent that can apply to people above certain income thresholds who do not have appropriate private hospital cover.
For the 2025–26 financial year, the base income threshold is $101,000 for singles and $202,000 for families, with the family threshold increased for dependent children. If your income is below the applicable threshold, the surcharge is not a financial reason to retain private hospital cover.
Lifetime Health Cover is different.
If you did not take out hospital cover by your Lifetime Health Cover base day and joined later, you can face a loading of 2 per cent for every year you were aged over 30, up to a maximum of 70 per cent.
If you have paid an LHC loading, it is removed after 10 years of continuous hospital cover.
But this is where anyone thinking about cancelling needs to pay attention.
People who have previously held hospital cover can generally use up to 1,094 permitted days without it during their lifetime without increasing their LHC loading. Go beyond the permitted absence rules and a loading may apply when you return.
In other words, cancelling today and simply picking cover up again years down the track may not leave you in the same position.
Then there is the rebate.
For the period from April 1, 2026 to March 31, 2027, the Australian Government Private Health Insurance Rebate still varies according to age and income. For people in the base income tier, it is 24.118 per cent for those under 65, 28.139 per cent for people aged 65 to 69 and 32.158 per cent for those aged 70 and over.
The Government has announced changes planned from April 2027 that would remove those higher age-based rebate rates, meaning people in the same income tier would receive the same rebate rate regardless of age.
That could change the arithmetic for older policyholders again.
What are you actually buying?
Once the tax considerations are put to one side, the question becomes much simpler: what does your policy give you for the money you are paying?
Depending on the policy, private hospital insurance can give you a choice of doctor and allow you to be treated as a private patient in a public or private hospital. As a private patient in a private hospital, you may also have greater choice about when you are admitted.
That distinction matters. Being privately insured does not mean jumping the queue as a private patient in a public hospital — public hospital waiting lists still apply.
Nor does private insurance guarantee a private room, eliminate waiting periods or mean you will never face an out-of-pocket bill.
APRA’s latest figures provide a useful reality check.
At June 30, 2026, 12.82 million Australians had hospital treatment cover — 45.8 per cent of the population.
More importantly for older Australians, hospital benefits paid per insured person rise markedly with age. APRA reports that the 75-to-79 age group accounted for the greatest total hospital benefits in its latest data.
During the June 2026 quarter alone, insurers paid $5.33 billion in hospital treatment benefits, while average hospital benefits per covered person reached $1,553.48 over the year to June 2026.
That does not mean every older Australian needs private cover. It does show why the calculation can look very different at 70 than it did at 40.
Check what your policy actually covers
This may be the most important part of the exercise.
Australian hospital policies are classified as Basic, Bronze, Silver or Gold, with “Plus” policies able to include additional clinical categories above the minimum requirements for their tier.
And the name on the policy matters less than the treatments listed inside it.
For example, cataract surgery and joint replacements are required categories under Gold hospital cover. Lower-tier policies may exclude or restrict them, although some Plus policies add categories beyond their standard minimum requirements.
So if you have been paying for the same policy for years, do not assume it automatically covers the treatments you are now most concerned about.
Open the policy document and look.
When cover may not stack up
There are perfectly legitimate circumstances in which a retired household may decide private health insurance is no longer worth the cost.
If premiums are putting serious pressure on a fixed household income, that matters. Insurance should not be considered in isolation from groceries, housing, energy bills and every other demand on the household budget.
Some people are also comfortable relying on the public hospital system and accepting that they may have less choice over their doctor or the timing of non-urgent treatment.
Then there is extras cover.
Hospital and extras are different products and deserve different calculations. Look at what you paid for extras over the past 12 months, then look at what the insurer actually paid back on your dental, optical, physiotherapy and other claims.
If the numbers are consistently a long way apart, ask whether the cover is still delivering value for you.
That does not automatically mean cancelling it. It means doing the calculation.
Do pensioners get cheaper private health insurance?
Not simply because they receive the Age Pension.
The major government assistance with private health insurance is the Australian Government Private Health Insurance Rebate, which currently depends on income and age rather than pensioner status alone.
Individual insurers may have their own offers, so check what applies to your policy rather than assuming your Pensioner Concession Card automatically produces a cheaper premium.
There is a third option
The private health insurance debate is too often reduced to two choices: keep it or cancel it.
There is another: change it.
You might be paying for things you no longer need while missing cover for things that have become more important. Your excess may no longer suit you. Your extras may not be earning their keep. Or another level of cover may deliver a better balance between premium and protection.
Which brings us to the question that is far more useful than “Is private health insurance worth it?”
Given my age, my health, my household income, what I actually claim and what my policy actually covers — is the policy I have today still the right one for me?
That is The Cover Check.
Before cancelling anything, understand exactly what you would lose, what waiting periods could apply if you returned later and whether Lifetime Health Cover could eventually affect you.
And before automatically renewing, understand exactly what you are paying for.
Because after years — sometimes decades — with the same insurer, the smartest move may not be keeping your cover or dumping it.
It may simply be checking it.
Worth knowing where you stand?
You can compare your health insurance with Starts at 60, or talk it through with an Australian adviser on 1800 31 23 60. There is no obligation and no pressure to switch – plenty of people call simply to find out whether their current cover still stacks up.
We’ll be following the legislation through to the Senate committee report in October and will come back to what it means from there. If you have a question about your own situation, leave it in the comments below. We read them, and they help shape what we cover next.
ALSO CHECK OUT THE REBATE CHANGE THAT COULD ADD HUNDREDS TO YOUR HEALTH COVER
IMPORTANT LEGAL INFO This article is of a general nature and FYI only, because it doesn’t take into account your personal health requirements or existing medical conditions. That means it’s not personalised health advice and shouldn’t be relied upon as if it is. Before making a health-related decision, you should work out if the info is appropriate for your situation and get professional medical advice.


 Proudly Australian owned and operated
Comments 0
Join the conversation. Comments are reviewed before they appear.
Be the first to comment.
Join the conversation
Tell us who you are to post a comment. We'll remember you next time.