Card surcharges disappears next week, check what you’re losing in return


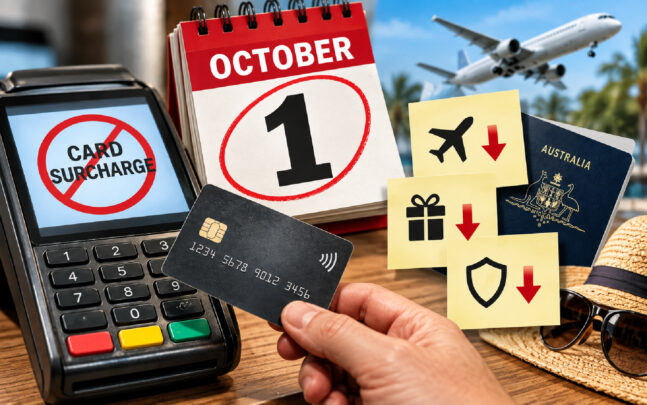
That annoying little extra charge at the EFTPOS terminal is about to largely disappear. From October 1, Australians paying by eftpos, Visa or Mastercard will no longer be slugged a separate card surcharge.
American Express and UnionPay are also removing surcharging from the same date, while PayPal follows from October 5.
For consumers, it sounds like a straightforward win, but it could be worth pulling your credit card out of your wallet and checking exactly what you’re getting for the annual fee.
Some of Australia’s biggest banks are changing rewards programs, card benefits, insurance and fees as sweeping Reserve Bank reforms reshape the economics of credit cards.
What changes on October 1?
The Reserve Bank reforms will allow card networks to ban merchants from imposing a separate surcharge simply because someone pays by card. At the same time, the RBA is reducing interchange fees paid between financial institutions when customers use their cards.
The maximum interchange fee on Australian-issued consumer credit cards falls to 0.3 per cent, with new limits also applying to debit and prepaid cards.
Businesses will still have to pay to accept cards, although the RBA expects lower interchange fees to reduce those costs.
There is a catch for shoppers. Businesses can incorporate payment costs into their overall prices, meaning the 1 or 1.5 per cent appearing separately on the payment terminal may vanish without every retailer simply absorbing the cost.
The credit card shake-up has started
For people with premium and rewards cards, the bigger question is what happens to the benefits attached to them.
CommBank will close its Awards program on September 29 and replace it with CommBank Yello points for eligible customers. Existing Awards points will generally be converted to Yello points, while CommBank has also announced changes affecting Qantas Frequent Flyer participation on some cards.
Westpac is making changes to some credit card fees, rates and its Rewards Points program from September 30. Changes to its complimentary credit card insurance take effect from October 1.
ANZ has also announced changes. From September 28, purchase interest rates on a range of ANZ cards rise to 22.49 per cent a year. Changes from October 28 include higher cash advance fees and, on some cards, new limits on the amount of spending that can earn Qantas or ANZ Reward Points. ANZ is also changing complimentary insurance benefits on some cards, although the timing varies between products.
So don’t assume the credit card sitting in your wallet still offers the same value it did when you signed up.
Check your travel insurance
This is particularly important for Australians who keep a premium credit card partly because it includes complimentary travel insurance.
For someone travelling overseas once or twice a year, that insurance can make a sizeable annual card fee easier to justify. But complimentary insurance differs significantly between cards.
Eligibility requirements, age limits, pre-existing medical conditions, excesses, trip-duration limits and minimum spending requirements can all affect whether you’re covered.
Anyone relying on credit card travel insurance for an upcoming holiday should check the latest policy wording rather than assuming last year’s conditions still apply.
The same goes for airport lounge passes and rewards points.
Some premium cards cost hundreds of dollars a year once annual card and rewards program fees are included. If the benefits change, the value equation changes with them.
What isn’t being banned?
October 1 doesn’t spell the end of every surcharge Australians encounter. The RBA makes clear the changes apply specifically to fees imposed because a customer chooses to pay by card.
Weekend and public holiday surcharges can stay, as can booking and service fees.
Businesses will also continue to incur costs for accepting card payments and can choose to reflect those costs in their advertised prices rather than adding a separate card surcharge.
Five things to check now
- Before October arrives, check the card you’re actually carrying rather than relying on what it offered when you signed up.
- Look at your annual fee, points earn rate, complimentary travel insurance conditions, airport lounge benefits and purchase interest rate.
- Then check any recent emails or notices from your bank.
- If you’re paying several hundred dollars a year for a premium card, the question is simple: are the benefits you’re receiving still worth the price?
- The surcharge disappearing from the EFTPOS terminal will be welcome. Just make sure another cost hasn’t quietly appeared somewhere else.


 Proudly Australian owned and operated
Comments 1
Join the conversation. Comments are reviewed before they appear.
Businesses will put that extra charge on items to cover the surcharge so paying with cash won’t save you anything.
Join the conversation
Tell us who you are to post a comment. We'll remember you next time.